Natural resource equities may appear to offer an alternative to commodity futures, but their returns reflect company-specific and broader equity market factors. We explore why the two exposures can behave differently and what that means for portfolio diversification and inflation protection.
The sharp rise in energy prices in 2026 has renewed inflation concerns and prompted investors to revisit commodity allocations. Broad, liquid commodity exposure is generally obtained through futures-based strategies, but natural resource equities may appear to offer a simpler, more familiar alternative. This reasoning is understandable: producers’ revenues are often linked to the commodities they sell. Yet producer equities also reflect costs, capital allocation, company-specific risks and broad equity market conditions. As a result, their inflation sensitivity and diversification properties can differ materially from those of commodity futures.
Different assets, different return drivers
It may seem puzzling that a natural resource company’s shares can behave differently from the underlying commodity. Why wouldn’t the price of copper, for instance, be the main driver of a copper producer’s stock? We would argue that several fundamental differences can cause their returns to diverge.
First, company-specific factors may affect a stock price without necessarily affecting the commodity price. Changes in dividend policy, corporate governance or earnings potential may influence a company’s stock price without any associated impact on the underlying commodity. The 2010 Deepwater Horizon disaster illustrates the distinction. BP’s shares fell sharply as investors reassessed the company’s cleanup costs, legal liabilities, operational risks and balance sheet pressures. BP later suspended its dividend. Broad crude oil futures did not experience a comparable BP-specific decline. The episode shows how an event can materially impair a producer’s value without having the same effect on the price of its commodity.
Second, market-level factors that affect equity prices aren’t necessarily reflected in commodity prices. These factors, often grouped generically as equity beta, include changes in earnings multiples, the regulatory environment and the tendency for stocks to move together. The substantial divergence between returns on energy futures and energy stocks in 2026 offers a timely example. Through Sept. 30, 2026, the Bloomberg Petroleum Subindex, a futures-based index of crude oil and refined petroleum products, surged nearly +130% year-to-date, while the S&P 500 Energy Index returned just +40%. Even during a strong commodity rally, natural resource equities may capture only part of the commodity’s gains.
Third, a company’s business model can dampen, delay or sometimes amplify its sensitivity to commodity prices. Hedging policies, long-term sales contracts, production volumes, operating costs, product mix and downstream operations all affect how changes in the underlying commodity prices flow through to revenue and earnings. These practices vary widely by company and industry, further limiting the extent to which commodity-related equities behave like direct futures exposure.
These differences matter because investors generally add commodities to a portfolio for a specific purpose, often to hedge inflation or increase diversification, rather than simply to express a view on resource companies.
Different exposures, different portfolio outcomes
For many investors, the appeal of commodities lies in their potential to hedge inflation and diversify a portfolio. These benefits may be diminished when exposure comes through publicly traded equities rather than commodity futures. Over the last 20 years, natural resource equities exhibited a lower correlation with changes in the Consumer Price Index (CPI) than the broad Bloomberg Commodity Index Total Return futures index—0.33 versus 0.60. While these correlations are sample-dependent, they are consistent with the broader point that producer equities carry substantial corporate and equity market exposures in addition to commodity-price exposure.
Natural resource equities also have tended to exhibit higher volatility and higher correlation with equities than commodities have.
Volatility and equity correlation: Commodities vs. natural resource equities (Jan. 2006 – Dec. 2025)
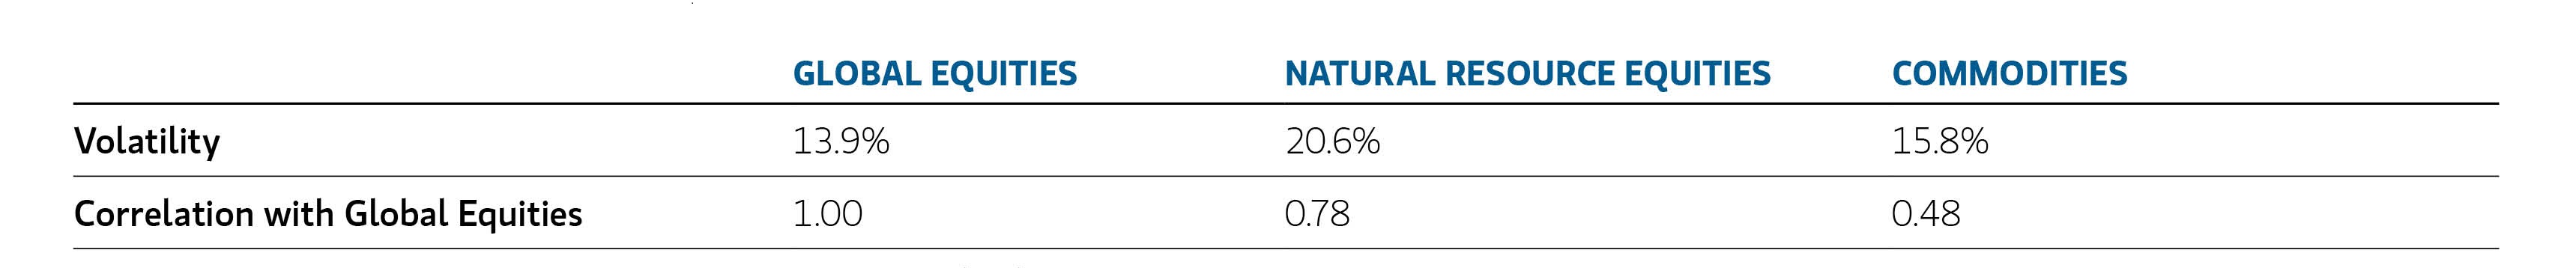
Sources: MSCI, S&P Dow Jones, Bloomberg, Parametric, 09/30/2026. For illustrative purposes only. Not a recommendation to buy or sell any security. It is not possible to invest directly in an index. Volatility as measured by standard deviation. Global Equities volatility and correlation measures are represented by the MSCI ACWI Net Total Return Local Index; Natural Resource Equities by the S&P Global Natural Resources Net Total Return Index; and Commodities by the Bloomberg Commodity Index Total Return.
Because natural resource equities have historically exhibited greater volatility and higher correlation with equity markets, an allocation to them may provide less portfolio diversification than a similarly sized allocation to broad commodity futures.
Risk management solutions for uncertain markets
Natural resource equities can play a useful role for investors seeking exposure to commodity-related businesses and their long-term earnings potential. But they should not be assumed to provide the same exposure as commodity futures. Their returns also reflect operating costs, management decisions, balance-sheet risk, valuation changes and broad equity-market movements. For investors whose primary objective is to hedge inflation or gain diversification from equities, a futures-based commodity allocation may be a more direct tool. The two exposures are related, but they are not interchangeable.
Definitions:
Correlation is a statistic that describes the size and direction of a relationship between variables, measured by a coefficient ranging from -1 to +1 indicating a stronger negative or positive relationship.
Risk Considerations
Trading in, and investment exposure to, the commodities markets may involve substantial risks and subject the Portfolio to greater volatility. In general, equity securities' values also fluctuate in response to activities specific to a company.
The views expressed in these posts are those of the authors and are current only through the date stated. These views are subject to change at any time based upon market or other conditions, and Parametric and its affiliates disclaim any responsibility to update such views. These views may not be relied upon as investment advice and, because investment decisions for Parametric are based on many factors, may not be relied upon as an indication of trading intent on behalf of any Parametric strategy. The discussion herein is general in nature and is provided for informational purposes only. There is no guarantee as to its accuracy or completeness. Past performance is no guarantee of future results. All investments are subject to the risk of loss. Prospective investors should consult with a tax or legal advisor before making any investment decision. Please refer to the Disclosure page on our website for important information about investments and risks.
11.30.2028 | RO 6091657