Before evaluating whether a long-short strategy belongs in a portfolio, we think it helps to understand what's actually happening under the hood. Let's start at the beginning.
Long-short investing has been quietly migrating from hedge funds into mainstream wealth management. The appeal is intuitive: A portfolio that can pursue returns on both sides of the market—while creating opportunities to harvest tax losses in nearly any environment—has value for investors seeking pretax excess returns and the potential tax benefits associated with realizing capital losses.
Being long is familiar
For most investors, being long a security is already well understood. When you buy a stock, you own it, so you benefit if the price goes up. For example, buy at $100, sell at $120, and you've earned a $20 capital gain. But if the stock falls, you have a capital loss.
In a long-only portfolio, conviction can be expressed through what investors choose to own. You buy stocks that you expect to do well and avoid those you think may decline. Here, avoiding a stock simply means not owning it. Seeking to buy low, sell high and pocket the difference is the default mode, how nearly every traditional portfolio is built. Mutual funds, ETFs and most separately managed accounts hold long positions exclusively.
Being short is the mirror image
By contrast, a short position involves selling a stock you don’t currently own, with the expectation that its price may decline. Rather than just avoiding the stock, shorting allows you to express a negative or unfavorable view of a company, with the potential to profit from it.
How can you sell shares you don’t own? By borrowing: Your broker lends you shares from another investor's account or their own inventory. You sell those borrowed shares at the current market price now, then you buy the same number of shares in the open market and return them to the lender later.
In the meantime, if the stock’s price falls, you buy back at a lower price and pocket the difference (minus any costs to borrow the security). If the price rises, you absorb a loss. For example, borrow and sell a stock at $100, buy it back at $80, and you’ve earned $20. But if the price climbs to $120, you’ve lost $20.
So where a long position profits when prices rise and loses when they fall, a short position does exactly the opposite.
Being both long and short may expand the opportunities
A long-short portfolio combines long and short positions within a single strategy, creating potential opportunities that wouldn’t be available in a traditional long-only approach.
The positions on each side may be chosen based on an investment thesis—going long stocks with attractive characteristics while shorting those that appear unattractive, with the goal of outperforming a benchmark. For example, an investor favoring high quality, undervalued stocks with positive momentum might rank the universe on those attributes, going long the top-ranked names while shorting the bottom.
Parametric's Custom Extension strategies apply this kind of multifactor framework to overweight stocks with the potential to outperform and short stocks that may lag the benchmark. Because active positions are maintained across the long and short sides of the portfolio, gains and losses have the potential to be generated continuously as market conditions evolve.
While the objective is appreciation in both the long and short positions, security selection and the broader market environment may influence actual outcomes. In stronger markets, long positions may be more likely to appreciate while shorts may incur losses; in weaker markets, the reverse may occur. As a result, both the long and short sides of the portfolio have the potential to generate capital losses that may be harvested for tax purposes.
The potential to generate tax-loss harvesting opportunities across a range of market environments is an important structural advantage of long-short investing. Unlike long-only portfolios, where harvesting opportunities may depend on broad market declines or company-specific setbacks, long-short portfolios can potentially source capital losses from either side of the portfolio.
Explore a multifactor approach to enhanced tax management
Measuring gross versus net market participation
To compare long-short strategies meaningfully, or to compare a long-short portfolio to a long-only portfolio, we need two simple measures of exposure:
Net exposure is the difference between long and short positions, which describes the portfolio's directional tilt—how much it participates in broad market moves.
Gross exposure is the sum of long and short positions, which describes the total capital deployed—including borrowed funds—and reflects the overall level of activity and leverage.
A 130/30 portfolio is 130% long and 30% short, with a net exposure of 130 − 30 = 100%. For a $10 million investment, that's $13 million in long positions and $3 million in short positions. Net exposure is $10 million—the same market participation as a traditional long-only portfolio—while gross exposure is $16 million.
A 200/100 portfolio with a $10 million investment is $20 million long and $10 million short. Net exposure of $10 million is identical to the 130/30 portfolio, but gross exposure is $30 million. More capital deployed toward factor-driven positions may offer greater potential for both investment alpha and tax-loss harvesting, but it also means higher cost and more risk—tradeoffs that any thoughtful evaluation of long-short would need to assess.
$10 Million Portfolio by Strategy
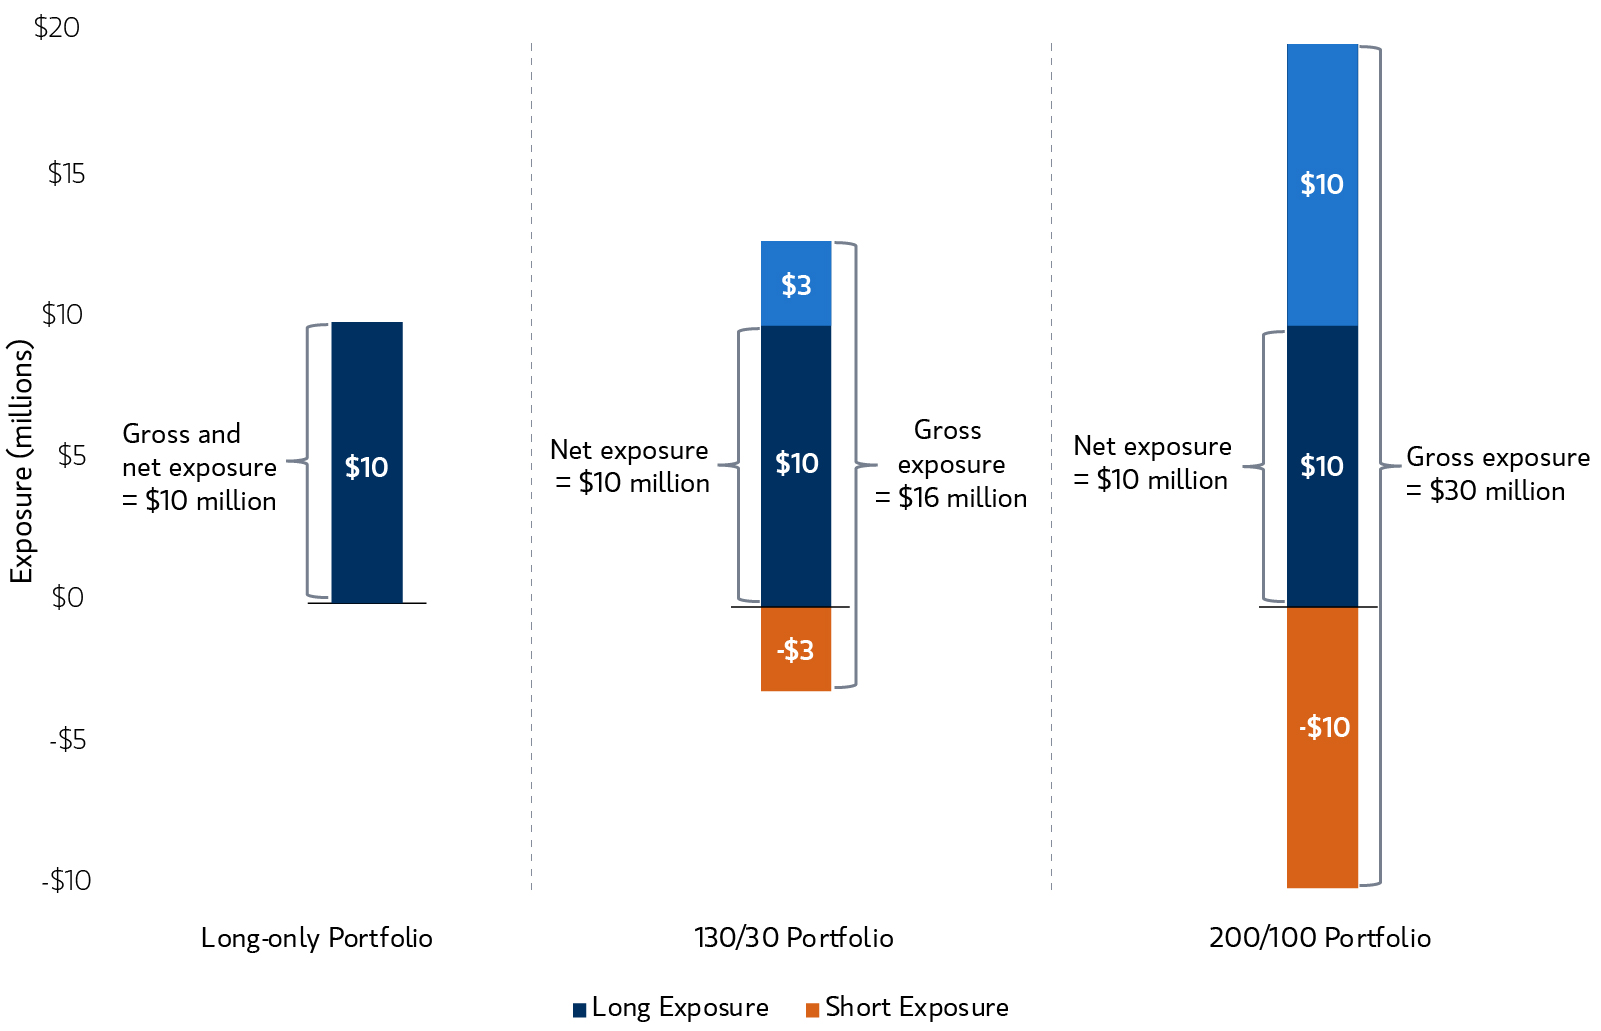
Source: Parametric, as of 8/28/2026. For illustrative purposes only. All investments are subject to risk, including the risk of loss.
The bottom line
The structural appeal of long-short investing lies in its ability to express active views on both sides of the market. By combining long and short positions selected through a disciplined factor framework, these portfolios may access sources of alpha that would be unavailable to long-only strategies, while also creating tax-management opportunities across a wider range of market environments—not just during market downturns. Note that a strategy engaging in short sales carries unique risks, including the potential for unlimited losses if a shorted security’s price were to rise.
In our view, the most important thing to understand about a well-built long-short portfolio is also the simplest: It must be a real investment strategy first. The long and short positions should be selected for genuine investment reasons—such as factor exposures, alpha opportunities and risk management—not engineered to manufacture tax outcomes. The potential tax benefits are a byproduct of disciplined active management, not the driver.
With that discipline in place, long-short can be a meaningful complement to a broader wealth management approach—offering the potential for enhanced pre-tax returns, more consistent tax-loss harvesting opportunities and a deeper expression of an investor's market views than a long-only portfolio could provide on its own.
Parametric and Morgan Stanley Investment Management do not provide legal, tax or accounting advice or services. Investors should consult with their own tax or legal advisors prior to entering into any transaction or strategy.
The views expressed in these posts are those of the authors and are current only through the date stated. These views are subject to change at any time based upon market or other conditions, and Parametric and its affiliates disclaim any responsibility to update such views. These views may not be relied upon as investment advice and, because investment decisions for Parametric are based on many factors, may not be relied upon as an indication of trading intent on behalf of any Parametric strategy. The discussion herein is general in nature and is provided for informational purposes only. There is no guarantee as to its accuracy or completeness. Past performance is no guarantee of future results. All investments are subject to the risk of loss. Please refer to the Disclosure page on our website for important information about investments and risks.
Risk considerations
Diversification does not eliminate the risk of loss. There is no guarantee that the investment objectives will be met.
There is no assurance that a separately managed account (SMA) will achieve its investment objective. SMAs are subject to market risk, which is the possibility that the market values of the securities in an account will decline and that the value of the securities may therefore be less than what you paid for them. Market values can change daily due to economic and other events (natural disasters, health crises, terrorism, conflicts, social unrest, etc.) that affect markets, countries, companies or governments. It is difficult to predict the timing, duration, and potential adverse effects (portfolio liquidity, etc.) of events. Accordingly, you can lose money investing in an SMA.
This investment strategy engages in short selling. A short sale involves selling a security borrowed by the investor, with the expectation that its price will decline, obligating the investor to later replace it at the current market price. Short sales carry unique risks, including potentially unlimited losses if the security’s price rises, additional costs for borrowing, and the possibility of forced closure under unfavorable conditions. Other risks include increased leverage, regulatory changes that may restrict short selling, and the need to provide collateral, which can reduce investment flexibility.
Investment strategies that seek to enhance after-tax performance may be unable to fully realize strategic gains or harvest losses due to various factors. Market conditions may limit the ability to generate tax losses. Tax-loss harvesting involves the risks that the new investment could perform worse than the original investment and that transaction costs could offset the tax benefit. Also, a tax-managed strategy may cause a client portfolio to hold a security in order to achieve more favorable tax treatment or to sell a security in order to create tax losses. Prospective investors should consult with a tax or legal advisor before making any investment decision.
09.30.2027 | RO 5942450